
Qualcomm's New Growth Engine Is Real. The Phone Business Is Still Bigger
Qualcomm's fiscal 2026 results show record automotive growth and a new data-center target, but handset revenue fell 26% in the latest quarter.
On this page
A chip company can announce a new market for years before that market changes its financial profile. Qualcomm’s November 4 results offer a better test than a product launch: the handset line is still its largest chip business, but the gap is narrowing as automotive and connected-device sales expand. The figures also show why investors should separate a quarter’s reported revenue from the company’s next-year data-center goal. [1] [2]
The handset decline is not a footnote
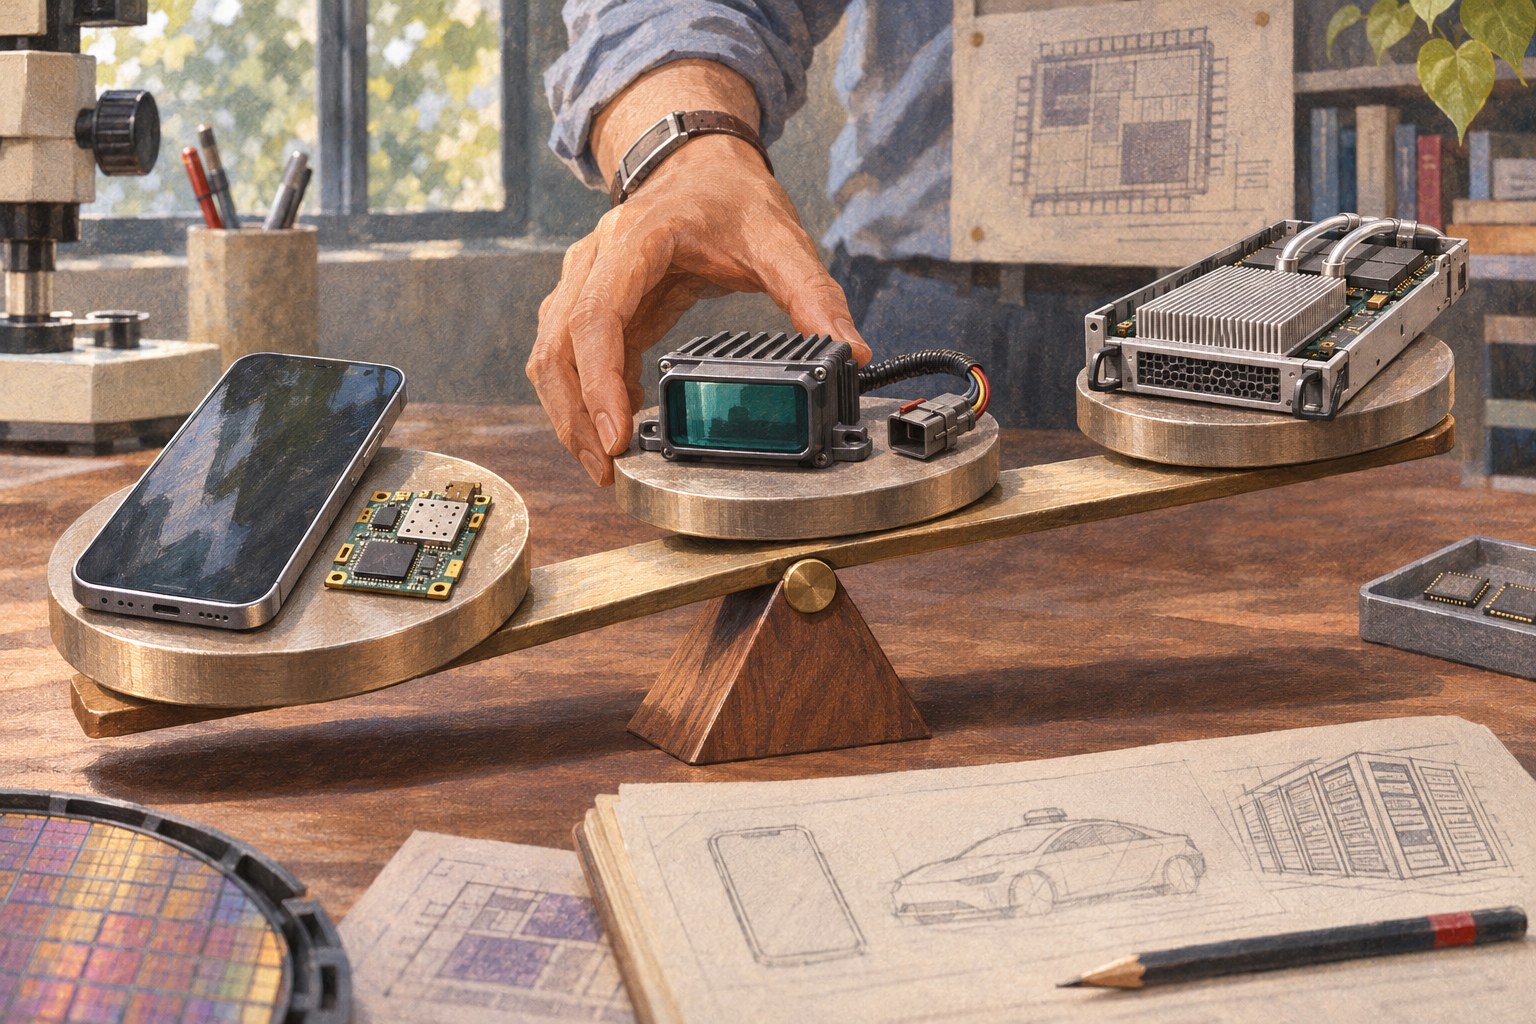
For the quarter ended September 27, Qualcomm reported $10.322 billion in GAAP revenue, down 8% year over year. Qualcomm’s chip segment, QCT, generated $9.015 billion, also down 8%. Within it, handset revenue was $5.137 billion, a 26% decline from the prior-year quarter. That one line was more than half of QCT revenue and almost three times the quarter’s automotive revenue. [1]
The drop deserves attention because handset demand and customer mix still shape the scale of Qualcomm’s business. Reuters reported that smartphone chip sales missed analyst expectations and that weaker Apple-related revenue weighed on the quarter. Those are market explanations, not a new segmentation in Qualcomm’s audited table; the company itself points to increased costs across wafer fabrication, assembly, packaging and memory among the industry pressures it expects to address through product pricing. [1] [2]
Automotive is growing from a much smaller base
Qualcomm’s automotive line rose to $1.990 billion in fiscal Q4, up 89% year over year. IoT revenue, a broader mix of connected devices, industrial uses and other products, reached $1.888 billion, up 4%. Together those categories are meaningful, but still smaller than handsets. The difference between rapid growth and a changed company is the base: 89% growth on automotive’s current base added about $937 million year over year, while handset revenue was still more than $5 billion for the quarter. [1]
This distinction matters when executives describe a “non-handset revenue inflection.” Qualcomm’s annual report figures show automotive revenue grew 52% to $6.004 billion in fiscal 2026 and IoT rose 8% to $7.132 billion. Those lines give the diversification argument real evidence. They do not establish that handsets no longer drive the company’s cycle or that another segment can replace them immediately. [1]
The data-center target belongs in the future tense
Qualcomm reiterated a $5 billion data-center revenue target for fiscal 2027 and said it expects non-handset revenue to grow more than 60%. It also disclosed a multi-generational product collaboration with Amazon for AI data centers. The collaboration gives the plan a named customer relationship, but the target remains management guidance, and the Q4 segment table does not show a $5 billion data-center operation already contributing to the quarter. [1] [3]
The execution question is not only whether Qualcomm can design a competitive accelerator. Data-center deployments depend on software, networking, memory bandwidth, qualification cycles and customers’ willingness to integrate another supplier into a high-stakes production stack. A target cannot answer those questions. Future filings will show whether the activity turns into recognized revenue, repeat orders and durable margins.
Read the profit numbers with the tax note beside them
Qualcomm reported fiscal 2026 GAAP net income of $13.628 billion, up from $5.541 billion a year earlier. That comparison is affected by a $5.7 billion tax benefit from releasing a valuation allowance. The company’s non-GAAP net income was $11.311 billion, down 15% year over year; that measure also requires caution because it excludes selected items. Neither figure should be quoted without its basis. [1]
A useful reading of this quarter is therefore narrower than the headline of a successful transformation: Qualcomm has growing automotive sales and a high-profile data-center opportunity, while smartphone chips remain the largest line and the most obvious source of near-term cyclicality. Readers following the shift should compare segment revenue, customer launches, recognized data-center sales and cash margins in subsequent filings—not treat the target as if it were already delivered. For related context, see our explainers on AI infrastructure bottlenecks and how data-intensive services handle shared storage.
Frequently asked questions
How much did Qualcomm's handset business fall?
Qualcomm reported QCT handset revenue of $5.137 billion for fiscal Q4 2026, down 26% year over year. Its automotive revenue rose 89% to $1.990 billion, while IoT revenue increased 4% to $1.888 billion.
Does Qualcomm already have a large data-center business?
No. Qualcomm reiterated a $5 billion fiscal 2027 data-center revenue target and described product collaborations with Amazon, but the target is forward-looking. The quarter's reported segment figures show handsets, automotive, and IoT, not a mature data-center segment of that size.
Why did Qualcomm's full-year net income rise while adjusted earnings fell?
Qualcomm's fiscal 2026 GAAP net income included a $5.7 billion income-tax benefit from releasing a valuation allowance. On its non-GAAP measure, full-year net income declined 15% year over year, so the GAAP increase does not by itself show stronger operating performance.
Sources & further reading
Keep reading
Box’s Agent Guardrails Put Content Permissions Around AI Actions
Box’s new controls restrict agent actions such as uploads and sharing, while audit trails and threat detection remain part of its roadmap.
Changshin’s Palantir Deal Connects Shoe Design Decisions to Factory Feedback
Changshin plans to connect footwear development, sample planning, and production data with Palantir; the rollout is still underway.
OpenAI’s Hardware Prototype Shows Where AI Engineering Still Needs Review
OpenAI says Astra helped design a talking device, but manufacturing tolerances and assembly details still required human review.
/* Comments */
Comments are offline right now — we reconnect automatically, nothing is lost.